Taxes, Premium Surcharges, and Social Security in One Plan
Built for financial advisors. Pick the accounts, the amount, and the timing. See the client's lifetime taxes, surcharges, and Social Security before and after, on one page.
RetirementAdvisorPro is planning software built for financial advisors. Its Roth tool answers the question a spreadsheet cannot: what does moving money from a traditional IRA to a Roth IRA cost the client over a lifetime, and what does it save?
Our Roth tool:
The numbers are big. In one household we modeled, a $2,000,000 pre-tax 401(k) cost the surviving husband or wife $795,611 in lifetime taxes and surcharges. Moving $80,000 annually to a Roth from age 65 to 72 cut that to $401,176. The full case is in how large 401(k) balances trigger retirement taxes.
A Roth conversion moves money out of a pre-tax account. The money moved is taxed as income that year. Since 2018 it cannot be undone, so the amount has to be right the first time. Five things decide whether it is.
| 2026 limit | Married filing jointly | Single |
|---|---|---|
| 22% rate ends at taxable income of | $211,400 | $105,700 |
| 24% rate ends at taxable income of | $403,550 | $201,775 |
| Premium surcharge begins at MAGI of | $218,000 | $109,000 |
| First required distribution | Age 73, or 75 if born in 1960 or later | |
The two limits that matter most, the brackets and the surcharge tiers, do not line up. Filling the 24% bracket crosses four surcharge tiers.
Timing makes it harder. The surcharge is set from the return filed two years earlier. A move in 2026 raises the 2028 premium, long after the recommendation was made.
Free calculators are a fair first screen. They take an account value, today’s rate, and a guess at a future rate, and stop there. They do not see the two-year lookback, the survivor filing single on roughly half the limits, or the required distribution growing every year. A spreadsheet that handles all of that is a project to maintain, not a tool to run in a client meeting.
Whether you evaluate RetirementAdvisorPro or any other conversion planner, hold it to one standard: it should model the whole household over the whole retirement, with a tax projection for every year, not a single-year rate comparison.
The Roth tab lives inside the client’s retirement plan. It already knows the income, the accounts, the Social Security, and the state. Three steps:
| Step | What happens |
|---|---|
| 1. You pick | Which pre-tax accounts to move, how much, when, and how long to spread it over. Whether to pay the tax from the move itself or from another account. |
| 2. You see | Before and after: lifetime taxes split into federal, state, and surcharges. The tax paid for the move, and the total savings. Social Security Impact, Medicare and IRMAA Impact, and Taxable Income Impact, each on an annual basis. A window chart with the lifetime cost of every length from one to fourteen, cheapest marked. |
| 3. You show | Turn the move into a full scenario, so it flows into Social Security claiming and Monte Carlo too. Put a Before & After slide in the client presentation with the same figures. Download the tables. |
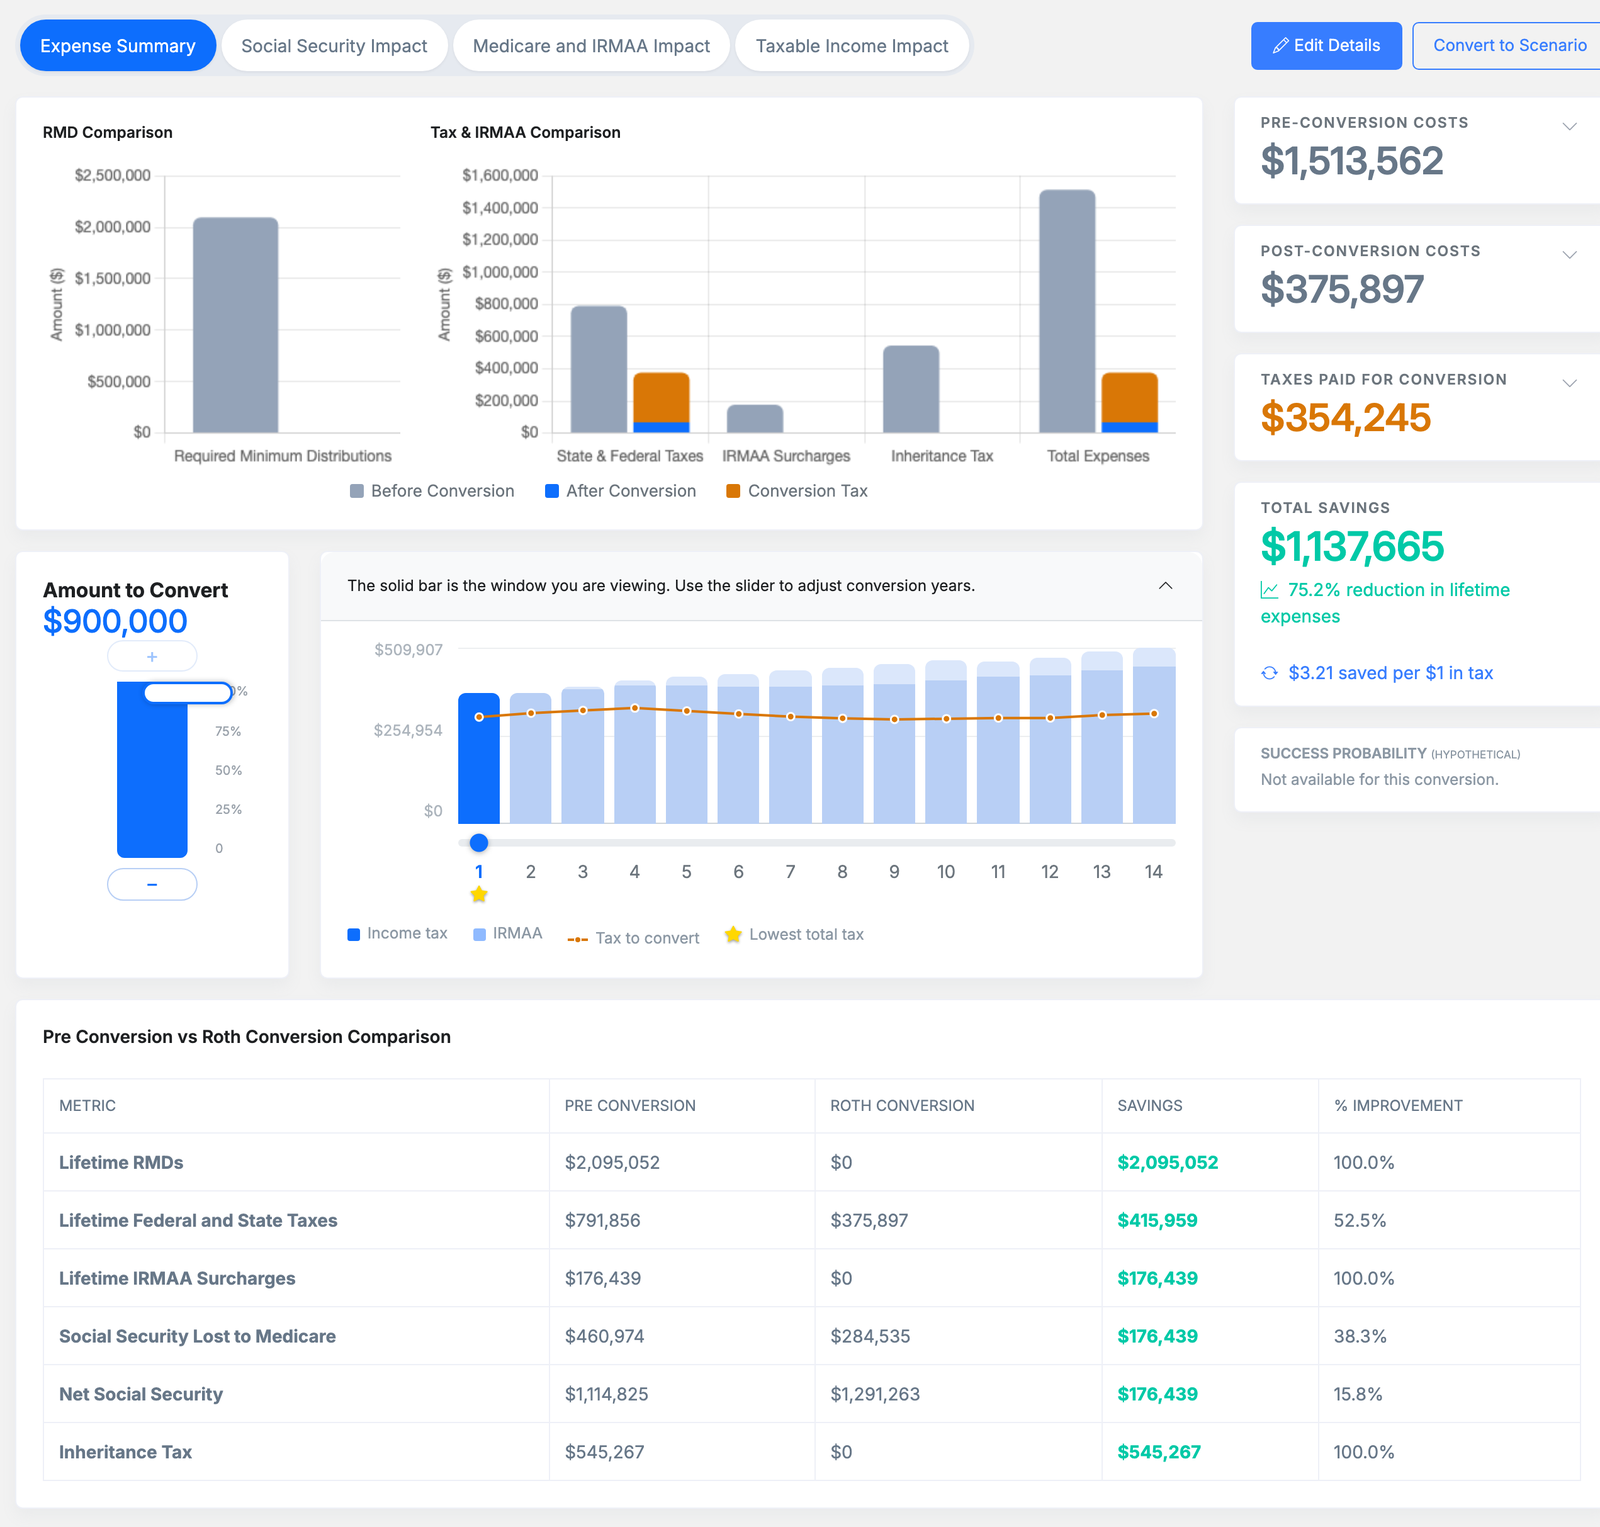
The fastest way to judge any conversion calculator is to run one of your own clients through it and look at the tax impact of each window. That is what the trial is for.
The surcharge. It is taken out of the Social Security payment, so crossing a tier shrinks the deposit the client sees. In one modeled single filer, the same $1,575,798 of Social Security paid out $193,305 more on the Roth path, and all of the difference was surcharge. The year-by-year math is in what moving to a Roth changes about Social Security.
The survivor. When a husband or wife dies, the survivor files single on roughly half the brackets and half the surcharge tiers, while the inherited IRA and its required distributions stay the same size.
| The $2,000,000 household, modeled from 73 to 95 | Lifetime taxes and surcharges |
|---|---|
| Both live | $533,325 |
| One dies at 74 | $795,611 |
| One dies at 74, after moving $80,000 annually to a Roth from 65 to 72 | $401,176 |
Software that stops at the joint return has skipped the period when the client is most exposed. RetirementAdvisorPro runs the survivor period in the same plan, with MAGI management and the income limits built in.
RetirementAdvisorPro is $139 per month per user. Every account starts with a 7-day free trial with full access. Build one real client, run the numbers, and decide. If one household signs because of the before-and-after page, the software has paid for itself.
For financial advisors only. RetirementAdvisorPro is software for advisory firms. We do not work with individual investors or retirees and cannot give personal tax or retirement advice. If you are working on your own move, please share this page with the professional who handles your taxes.
Prefer to see it on a real case first? Book a live demo below and we will model one of your households on the call: the schedule, the rate it lands in, the surcharge it triggers, and the survivor period.
Advisors: Model a Client Live
Then keep exploring the rules behind every recommendation.
Roth Strategy
Surcharges & MAGI
Brackets & Premiums
Disclaimer: This article is educational content for financial professionals. It is not investment, tax, legal, insurance, or accounting advice, and it is not a recommendation of any security, strategy, or product. Any examples, figures, and calculations are hypothetical illustrations based on the stated assumptions and on tax and Medicare rules in effect at the time of writing, which are subject to change; they are not predictions or guarantees, and individual results will differ. RetirementAdvisorPro is not a registered investment adviser, broker-dealer, insurance agency, law firm, or accounting firm, and nothing here creates an advisory or professional-client relationship. Consult a qualified financial, tax, or legal professional regarding your specific circumstances. See our full disclosures.
Co-Founder of IRMAA Certified Planner, Founder of RetirementAdvisorPro
Mark Annese is an IRMAA Certified Planner specializing in helping financial advisors navigate Medicare income-related adjustments and optimize client retirement income strategies.
Common questions about our platform and services
Join financial advisors who are providing world-class retirement planning services with our AI-powered platform.
